Rebuilding Together
A Message from Our Family to Yours
When disaster strikes close to home, it impacts more than just structures—it touches the heart of our community. If your family was affected by the recent Spokane fires, we want you to know something important from the very beginning: You are not alone.
At Dykon Construction, we are more than just a local construction company. We are a family-owned and operated business, and we have called Spokane home for over 20 years. We’ve raised our families here and built our lives alongside yours. Seeing our community face the devastation of these fires broke our hearts, and we want to step up as a trusted resource and neighbor to help you navigate the road ahead. Please see the Free resources below, and if you have any questions, please feel free to reach out. No obligations, just a local business operating on the golden rule.
Your Rebuilding Resource Hub
Taking the first steps after fire damage can feel overwhelming, especially when you are dealing with insurance companies, permits, and countless decisions. To help make this process clearer and less stressful, our team has put together a guide and downloadable checklist to help get started in the right direction.
Spokane Fire Rebuild Guide for Homeowners
If your home burned in the August 2026 Spokane Complex fires (Old Trails, Autumn Lane, Fairview) or the June Upriver Fire, you have three paths: rebuild what you had, rebuild something different, or sell the lot and move on. Every path starts with the same two jobs:
clearing the site legally and getting your insurance claim right.
This guide walks through each step in plain language, with the local agencies, phone numbers and rules that apply here. It is free to use and share.
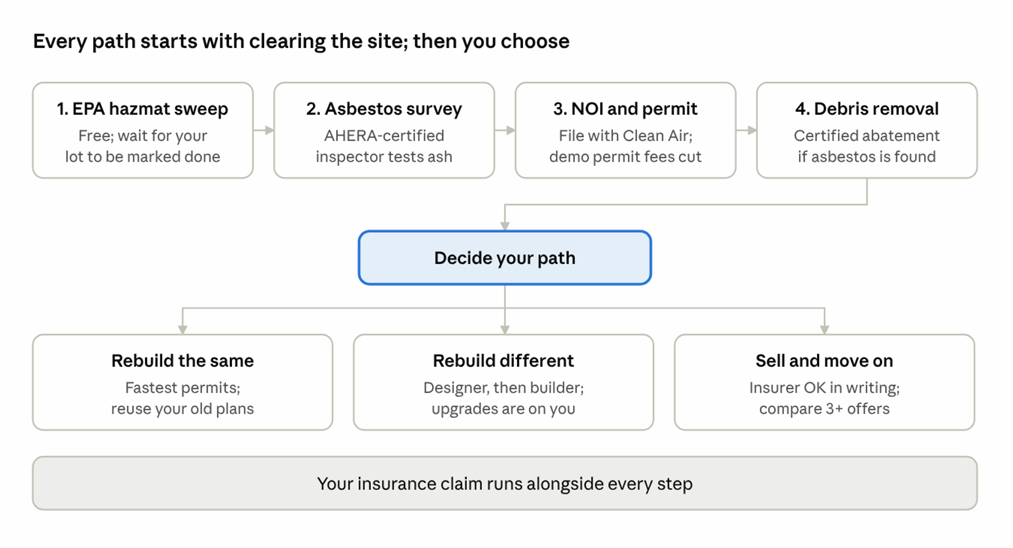
The four cleanup steps happen in order for everyone. Only after the site is clear does your choice of path change what comes next.
Where things stand (as of September 29, 2026):
- About 615 primary residences were destroyed in Spokane County, per the state's damage assessment. (Governor's office)
- EPA has been clearing household hazardous materials from burned lots. Your lot must be marked complete before you move on to asbestos testing and debris removal. (EPA)
- On September 28, Gov. Ferguson asked the President for a Major Disaster Declaration. If approved, it opens FEMA individual aid and SBA disaster loans. It is not approved yet.
- The City of Spokane and Spokane County have both cut or deferred permit fees and are fast-tracking "like-for-like" rebuilds.
Rules and programs are changing week to week. Check the linked agency pages before you act on any date, fee or dollar amount here.
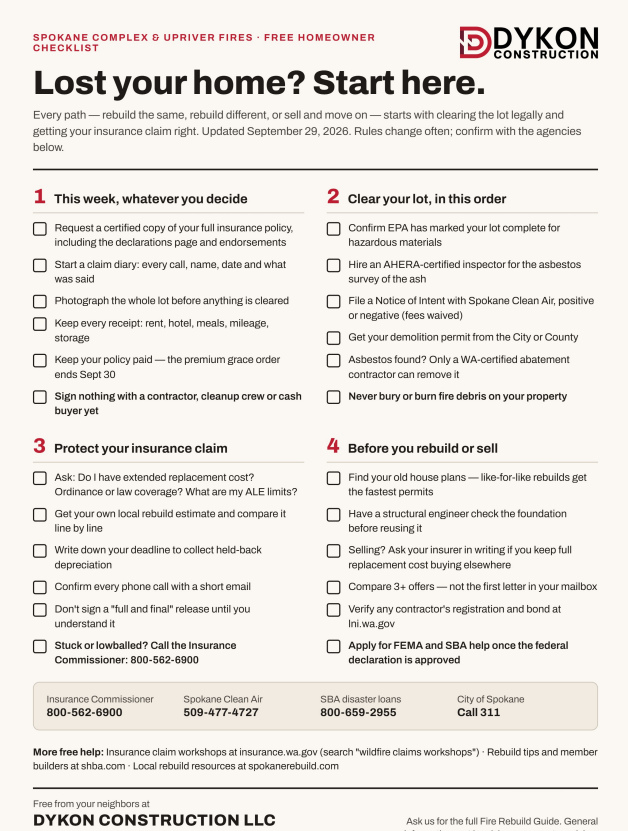
Do these three things this week, no matter which path you choose:
- Get a complete, certified copy of your insurance policy, including all endorsements and your declarations page.
- Start a claim diary: every call, email, name, date and what was said.
- Do not sign anything with a contractor, cleanup company or cash buyer until you have read the sections below.
Step 1: Clear the site the legal way
No debris leaves your lot, and no building permit is issued, until an asbestos survey is done and a Notice of Intent is filed with Spokane Clean Air. Skipping this step can bring fines and stop your rebuild cold.
The order of operations:
1. EPA hazardous materials sweep. EPA crews remove propane tanks, fuels, paint, pesticides, batteries and similar items at no cost. Wait until your property is marked complete before any other work. If you opted out, you must handle these materials yourself. (EPA)
2. Asbestos survey. Hire an AHERA-certified building inspector. They sample the ash and debris in a grid pattern across the burn footprint. This is required for every damaged or destroyed structure, no matter how old the house was. (Spokane Clean Air)
3. File the Notice of Intent (NOI) with Spokane Clean Air, whether the survey is positive or negative. Clean Air is waiving NOI fees and waiting periods for fire-affected owners.
File online from the link above.
4. Get a demolition/debris permit from the City of Spokane or Spokane County, depending on where you live (see Step 4).
5. Remove the debris.
Survey negative: you or a Washington-licensed contractor can remove it. Keep a copy of the survey with every load.
Survey positive: a Washington-certified asbestos abatement contractor must remove the asbestos-containing ash and debris.
6. Foundation and soil. After debris is gone, have the foundation evaluated before assuming it can be reused (see Step 3).
Rules that catch people:
Fire debris counts as demolition under state law. You cannot bury it on your property or burn it.
Do not haul loose, unbagged ash. The Waste-to-Energy Facility does not accept ash.
Call the disposal site before you haul anything.
"Cleared for re-entry" does not mean safe. Wear an N95 or better, gloves, long sleeves and boots on the lot. (SRHD)
Sifting for keepsakes is allowed, but keep it gentle and wear protection.
Who pays? Right now, homeowners are responsible for asbestos testing, abatement and debris removal. Most homeowners policies include debris removal coverage, so check yours before paying out of pocket. The state's September 28 FEMA request includes debris-removal funding for local governments. Watch for any announcement of a program covering private lots.
Before hiring a cleanup company, get a written, itemized bid: survey, abatement, hauling tons, disposal fees, foundation removal and erosion control priced separately. Your insurer will want that detail to reimburse you..
Step 2: Get your insurance claim right
The biggest financial risk in a rebuild is being underinsured and not knowing it. After the 2023 Gray and Oregon Road fires, the Insurance Commissioner's office found about two thirds of affected households were underinsured. (KING 5)
Know what each part of your policy pays for:
| Coverage | What it pays for | What to ask |
|---|---|---|
| A: Dwelling | Rebuilding the house | Do I have extended or guaranteed replacement cost? What is the extra percentage? |
| B: Other structures | Garage, shop, fences, sheds | Is it separate from Coverage A? |
| C: Contents | Your belongings | Will you advance part of it before I finish an itemized inventory? |
| D: Loss of use (ALE) | Rent, extra mileage, meals, storage while displaced | What is the time limit and dollar limit? Can you pay in advance? |
| Debris removal | Site cleanup, often including asbestos work | Is it inside or on top of my dwelling limit? |
| Ordinance or law | Costs to meet current building and energy codes | How much do I have? This can be a large gap on older homes. |
How to avoid getting shortchanged:
- Get your own rebuild estimate. The adjuster's number comes from estimating software. Ask a local builder for a detailed estimate of your specific home at today's Spokane prices, then compare line by line.
- Understand the "holdback." Many policies pay actual cash value first and hold back depreciation until you rebuild or replace. Find your policy's deadline for collecting it and write it down.
- Put everything in writing. After every call, send a short email: "To confirm our call today, you said..."
- Don't sign a "full and final" release or cash a check marked that way without understanding it. Partial payments are normal and fine.
- Your mortgage lender is probably on the check. Dwelling payments are often made out to you and your lender. The lender may hold the money and release it in draws as work is done. Plan your rebuild cash flow around that.
- Contents: Use a spreadsheet by room. United Policyholders has free inventory tools and a Spokane-specific library. (uphelp.org)
- Keep every receipt for living expenses, mileage and emergency purchases.
If the claim stalls or the numbers look wrong:
1. Ask the adjuster, in writing, for the complete estimate and the policy language behind any denial.
2. Call the Washington Insurance Commissioner's consumer hotline, 800-562-6900. It is free, and they can open a complaint with your insurer. The office also runs monthly wildfire claim workshops. (OIC)
3. Consider a public adjuster or attorney for large disputes. Public adjusters must be licensed in Washington and take a percentage of your claim, so compare fees. (OIC)
Premium relief ends soon. The Commissioner's emergency order, which gives a 45-day premium grace period and blocks cancellation for nonpayment, runs through September 30, 2026. Keep your policy paid. (OIC)
Step 3: Rebuild the same, rebuild different, or sell
There is no wrong answer, but each path has a different timeline, cost and paperwork trail.
Take your time: you do not have to decide in the first weeks, as long as you know your insurance deadlines.
| Rebuild the same | Rebuild different | Sell the lot and move on | |
|---|---|---|---|
| Fastest when | You have your old plans or a recent plan set | You have plans drawn and budget confirmed | You have a buyer and your insurer's written OK |
| Permit speed | Fastest: "like-for-like" fast track in City and County | Standard review; longer | None needed |
| Code relief | Proposed older energy code option applies to you | Proposed option may apply to you as original owner | Buyer must build to current code |
| Main risk | Rebuild estimate exceeds your dwelling limit | Upgrades not covered by insurance | Selling the lot too cheap |
| First call | A builder for a rebuild estimate | A designer, then a builder | Your insurer, then a real estate broker |
Rebuilding what you had
- Find your old plans. The City will reuse plans on file; one 2023 home got its rebuild permit in two days. Plans reused from the last five years pay no plan review fee. (Inlander)
- Don't assume the foundation is reusable. Intense heat can weaken concrete and rebar, and debris crews can crack it. Have a structural engineer evaluate it in writing before your builder prices around it. A good foundation can save tens of thousands; a bad one reused can cost far more later.
- Energy code relief is proposed, not final. The Governor is asking the State Building Code Council to let owners who held title at the time of the fire rebuild to an earlier energy code. (Governor's office)
Rebuilding something different
- Bigger, smaller, a different layout, or an ADU first. The City has proposed letting owners permit and live in an ADU before the main house is finished. (City of Spokane)
- Insurance generally pays what it would cost to replace your old home. Anything beyond that is yours to fund.
- This is the moment to build fire-resistant: Class A roof, ember-resistant vents, noncombustible siding near grade, and a cleared 5-foot zone around the house. Ask your insurer whether these lower your premium.
Selling the lot and moving on
- Ask your insurer in writing whether you can collect your full replacement cost by buying another home elsewhere instead of rebuilding. Policies differ; some cap it at what rebuilding on your lot would have cost. Get the answer before you list.
- One offer is not a market. Cash buyers are already sending letters. Get your lot's assessed value, talk to a licensed broker, and compare at least three offers.
- Your lot may be worth more to you than to a buyer. The proposed energy code relief does not transfer to a new owner.
- Talk to a tax professional before closing. Insurance proceeds plus a lot sale can trigger capital gains questions, and special IRS rules apply to disaster losses.
Step 4: Permits and rebuild relief
Who issues your permits depends on whether your lot is inside Spokane city limits or in unincorporated Spokane County. Both have cut fees and put fire rebuilds at the front of the line, especially for homes rebuilt on the same footprint.
| City of Spokane | Spokane County | |
|---|---|---|
| Demolition permit | Fee reduced to $35; processing and technology fees waived | Inspection fee waived 100% |
| Building permit fees | Proposed: defer fees until certificate of occupancy | Inspection fees cut 50% |
| Review speed | Existing plans: as fast as 2 days. Similar rebuilds: about 4 to 6 weeks | Same footprint and location: 5 to 7 day target |
| Other relief | Proposed: like-for-like planning waivers, ADU before main house, no utility connection charge (GFC) for the same meter size | Temporary on-site housing allowed with conditions; call to discuss |
| What you need | Asbestos survey and Clean Air NOI before building permits | Signed Wildfire Damage Permit Attestation Form |
Sources: City of Spokane, KZZU, Inlander, Spokane County Resolution 2026-0500 coverage, County rebuild FAQ.
"Proposed" items were emergency ordinances under consideration in mid-September.
Confirm their status with the City's Development Services Center before counting on them.
State relief: Gov. Ferguson announced he will waive the state fee on building permits in affected counties and let Ecology exempt debris piles from permits to speed removal. (Governor's office)
Check your lot's status on the City's REBUILD Spokane dashboard, which shows every affected structure and will add permit status. If your property is listed wrong, the dashboard has a link to report it.
Money beyond insurance
Insurance is the main source of rebuild money, but several other programs can fill gaps.
Some are open now; the federal ones depend on the disaster declaration requested September 28.
| Program | What it offers | Status (Sept 29, 2026) |
|---|---|---|
| FEMA Individual Assistance | Grants for housing and repairs, up to the $42,500 program maximum; meant for gaps, not a full rebuild | Requested, not yet approved. Apply once approved, even if unsure you qualify |
| SBA disaster loans | Low-interest, long-term loans for uninsured or underinsured losses. After the 2023 fires: up to $500,000 for a home, $100,000 for belongings | Opens only after federal approval; application windows are short |
| State Individual Assistance | Cash for immediate needs; nearly $1 million paid to 600+ households so far | Open: mil.wa.gov/wildfire assistance |
| DSHS Disaster Cash Assistance | Short-term cash help | Open through October 30: DSHS |
| Sales tax rebate on rebuild costs | About $36,000 back on a $400,000 Spokane rebuild, per the Governor's example | Proposed legislation; not law yet |
| Property tax relief | Assessor removes the home's value from the date it was destroyed; refunds if you already paid | In effect: call the Spokane County Assessor |
Sources: Governor's office, Spokane County SBA info (2023 fires), Spokesman-Review.
Also worth a call:
- Federal tax extensions have been granted for affected individuals and businesses. Ask a tax professional about casualty loss rules too.
- Assessor rebuild exemption. After the 2023 fires, a state law let owners lock in their home's prior value for three years after rebuilding. Ask whether it applies to you.
- Your mortgage servicer. Many offer forbearance after declared disasters. Ask, and get any agreement in writing.
- Spokane Region Long Term Recovery Group helps households with unmet needs after insurance and aid run out.
Choosing a contractor and avoiding scams
After every big fire, out-of-area crews and cash buyers arrive fast. A good local builder will
never pressure you to sign today.
Red flags, walk away:
- Knocks on your door or leaves a flyer on your burned lot and pushes you to sign now.
- Wants a large deposit before any work or permit, or cash only.
- Offers to "handle your insurance" or asks you to sign over your claim. In Washington, only a licensed public adjuster or an attorney can negotiate your claim for you.
- Isn't registered with Washington L&I, or the registration name doesn't match the contract.
- Won't give a written, itemized contract.
Check before you hire:
- Look up their registration, bond and insurance on L&I's "Verify a Contractor" tool at lni.wa.gov
- Ask for a certificate of liability insurance naming you
- Call three recent clients, ideally from fire or insurance rebuilds
- Ask how many fire rebuilds they are taking on at once, and who will run your job day to day
- Ask if they will go through your insurer's estimate line by line with you
What your contract should include:
- A clear price: fixed price, or cost-plus with a guaranteed maximum
- A payment schedule tied to finished work and your lender's draw schedule, not the calendar
- Allowances for finishes, with dollar amounts
- A written change-order process: no extra work without your signature and a price
- Lien waivers from subs and suppliers with every payment
- A start date, schedule and warranty terms
- The lien disclosure statement Washington requires on residential jobs over $1,000
Report scams to the Washington Attorney General's consumer protection line and to L&I.
Resource directory
| Who | For | Contact |
|---|---|---|
| WA Insurance Commissioner | Claim problems, complaints, free advice | 800-562-6900 · insurance.wa.gov |
| WA Insurance Commissioner workshops | Free monthly wildfire claims workshops for Spokane fire survivors | Workshop dates |
| Spokane Clean Air | Asbestos rules, Notice of Intent, certified provider list | 509-477-4727 · spokanecleanair.org |
| EPA | Household hazardous materials sweep status | epa.gov |
| Spokane Regional Health District | Safe re-entry and cleanup health guidance | srhd.org |
| City of Spokane | City permits, REBUILD Spokane dashboard | Spokane 311 · my.spokanecity.org |
| Spokane County Building and Planning | County permits, attestation form | spokanecounty.gov |
| Spokane County Solid Waste | What debris is accepted where | spokanecounty.gov |
| Waste to Energy Facility | Accepted fire debris (no ash) | 509-625-6580 |
| WA Emergency Management | State Individual Assistance | mil.wa.gov |
| SBA Disaster Loans | Once the federal declaration is approved | 800-659-2955 · sba.gov/disaster |
| Spokane Home Builders Association | Rebuilding tips, disaster recovery resources, member builder directory | shba.com fire rebuild tips |
| Rebuild Spokane | Local rebuild resources and contractor directory | spokanerebuild.com |
| United Policyholders | Free claim guides and inventory tools | uphelp.org/2026SpokaneFires |
| WA Labor and Industries | Verify a contractor | lni.wa.gov |
About this guide
This guide was put together by Dykon Construction LLC, a family-owned residential builder serving Spokane and North Idaho since 2022, as a free resource for our neighbors. You are welcome to print it, share it and pass it along. We will keep it updated as programs and rules change.
Questions about your rebuild, your foundation, or your insurer's estimate? We're glad to talk, with no obligation.
Dykon Construction LLC · Keegan Petersen, Owner · WA Contractor Reg. DYKONC*763JE
· (509) 795-9919 · hello@dykonconstruction.com · dykonconstruction.com
This guide is general information, not legal, insurance or tax advice. Every policy and property is different. Check current details with the agencies listed and talk to a licensed professional about your situation.